Interest Rate Sensitivity and Strategic Shifts
DE-fense! clap-clap DE-fense! clap-clap - No, we're not at a basketball game, I'm shouting at your bond portfolio. We need to consider being more defensive with that part of your portfolio. Bonds are like a teeter-totter on the playground and when rates go up on one side, the value goes down on the other side. The farther out you are, the more it moves.
Since 2020, the heavy use of long-term bonds was something that I was against. So one of the first things I did after creating TerraFirma Wealth Partners was to reduce or eliminate the long-term bond investment (SPTL) and the risk that went along with it. We shifted to a combination of short (BSV) and medium term (LQD) bonds.
Earlier this month in June, we made a second step in the same direction. For many portfolios, we reduced or eliminated the medium term bonds to use a combination of short (BSV) and ultra-short term bonds (VUSB).
Quantifying Risk
What does risk actually mean in bonds and bond funds? An important measurement is Duration which measures how sensitive a bond's value may be to interest rate risk. A Duration of 1 means that if interest rates go up or down 1%, then you may experience a corresponding decrease or increase in the value of your bonds. If your Duration is 10, then you may experience a corresponding 10% decrease or increase in the value of your bonds. See this chart:
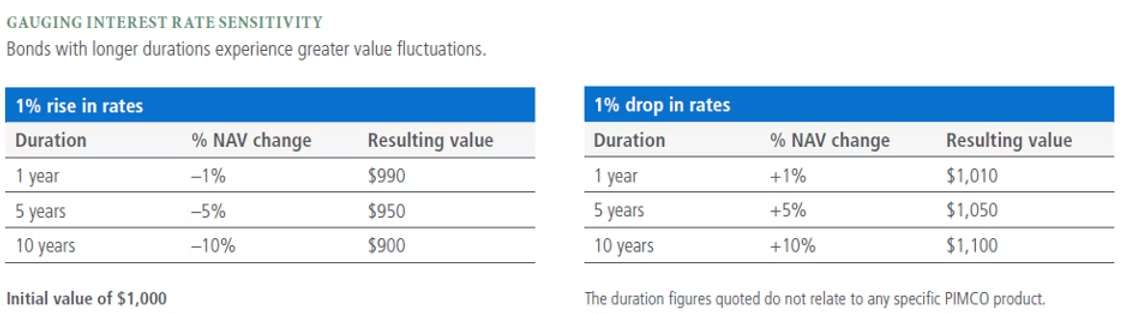
The Duration of SPTL (the position that was sold at my first opportunity) is 14.62 as of this writing (6/17/25) and the Duration of VUSB (the recently added position) is currently 0.9. So if interest rates rise 1%, SPTL may lose 14.62% while VUSB may lose 0.9%.
Implementation Into Your Portfolio
With the ever increasing Federal deficit, are you willing to bet that long-term rates are about to go down? As the Federal balance sheet looks less and less healthy, firms generally have to offer higher interest rates to entice people to buy the bonds.
Quick trivia: Anyone remember what interest rates Greek bonds offered in 2012 as they were going through extreme austerity measures? Any guesses? 29.24% in February of 2012, when just three years earlier it was 4.56%. I'm not saying the United States is about to become Greece, but this illustrates the point that bond interest rate risk is very real.
The objective of bonds in your portfolio is to provide stability and generate income that is hopefully above inflation. So what are we giving up in yield by going from long-term to short-term bonds? As it turns out, not a whole lot. SPTL has a yield of 5.01% and VUSB has a yield of 4.8%. 0.21% more yield for more than 15 times the risk. It's pretty clear to me what type of bonds are better able to hold your portfolio together. Let's focus on playing defense when the future of interest rates is uncertain.
Alphabet Soup: RMDs & QCDs
We are already halfway through the year, so let's check on those Required Minimum Distribution (RMDs)! If you will be age 73 or over by the end of the year, you will need to take an RMD out of your pre-tax IRA and 401k (so not Roth IRAs or Roth 401k's). For a vast majority of TerraFirma clients, we have monthly or annual withdrawals already scheduled. In which case, your work is done and we will calculate the amount necessary to satisfy the requirement and ensure it is done before the end of the year. For the individuals who need to take an RMD and do not have a scheduled withdrawal, Kimberly will be sending you notification that we still need to plan for this. Fortunately, we have until the end of the calendar year to get this done.
If you are subject to RMD's you also have the option to gift part of the RMD (or any withdrawals from IRA's) directly to a non-profit organization. This is called a Qualified Charitable Distribution (QCD) and counts against the RMD amount. It also reduces your Adjusted Gross Income (which is an uncommon deduction). Sometimes doing so can put you just below certain thresholds to reduce Medicare Premiums by thousands of dollars. A clear instance of receiving more by giving! This is something I've been keeping an eye out for when doing the tax return analysis. On that note, if you have submitted your returns and haven't received your analysis yet, please give me a bit more time as I'm still working through them.
The Bill Is Due
Many eyes are on the Big Beautiful Bill, including mine. There's little use in speculating what the end result will be, so I won't waste my breath here doing that. I do want to let you know that I am proactively watching it and the moment it becomes law, I will update my recommendations accordingly. My suspicion is that for most people, there will be nothing that needs to be done immediately. If there is, I will reach out to you directly to let you know.
Altruist Rebranding: All New Look, Same Old Formula
Over the coming weeks, Altruist will be launching a full rebrand, including a modern new look, updated website and app design, and more streamlined communication. If you use the Altruist mobile app, you'll notice these updates when you log in. The layout will be cleaner, navigation will be easier, and you'll have access to even more information like cost basis data and other key portfolio details.
You'll also start seeing redesigned emails from Altruist related to things like account statements, money movement, and confirmations. These updates are all part of Altruist's commitment to clarity, transparency, and a better overall experience.
I'm sharing this with you in advance so you're not caught off guard. The changes are purely visual. Your account access and security remain exactly the same.